Royalty Ridge

Phone : (307) 463-7776

Oil and gas royalties can provide ongoing income from mineral production, but their value is not determined by a single number.

For a producing royalty interest, buyers and owners typically need to consider the expected future cash flow from production, the owner’s share of that production, commodity prices, production trends, lease terms, location, and the potential for additional development.

In Texas, the Railroad Commission maintains production and permitting records that can help royalty owners research production associated with oil and gas properties. The Commission notes that reported production data can be updated as revised or corrected reports are received.

If you are considering selling an oil or gas royalty, understanding these factors can help you evaluate the asset before comparing offers.

One of the first things a buyer is likely to examine is the royalty income currently being generated.

Recent royalty statements can show:

  • Monthly or periodic revenue
  • Oil and gas volumes
  • Price information
  • Owner interest
  • Taxes and deductions
  • Net payment

Texas royalty-payment information can include property identification, sales month, volume sold, price per barrel or Mcf, deductions, net value, owner decimal interest, and other information.

Consistent royalty income provides useful historical information when evaluating an interest.

However, current income should not automatically be treated as future income. Oil and gas production can change over time

Production history is another major factor in evaluating a royalty interest.

A buyer may examine how production has changed over time and whether the underlying wells are producing consistently.

For example:

Strong recent production

  • Strong recent production
  • Historical production analysis
  • Production trend
  • Future production estimate
  • Potential royalty value

Texas provides public production records through the Railroad Commission’s Production Data Query system. The Commission explains that production is reported by lease rather than individual well in its system and that online production data can have a reporting lag.

This makes historical production data an important starting point for understanding an existing royalty interest.

The percentage of production revenue attributable to the royalty owner can have a substantial effect on value.

For example, two properties might generate similar gross production but provide different royalty interests to their owners.

A higher royalty percentage can result in a larger share of revenue, all else being equal.

The applicable royalty rate is determined by the relevant lease and ownership documents. The Texas Railroad Commission specifically notes that lease and royalty matters are generally private contractual matters outside the Commission’s authority.

This is why owners should review the actual lease and related documents rather than relying solely on assumptions about their royalty percentage.

Commodity prices can directly affect the revenue generated from production.

If the underlying interest produces oil, changes in crude oil prices can affect the revenue associated with that production.

Natural gas prices are similarly influenced by supply and demand. The U.S. Energy Information Administration identifies natural gas production, storage, imports and exports, weather, economic growth, and competing fuels among the factors that influence natural gas prices.

Oil prices also respond to changing market conditions, including supply, demand, and petroleum inventories.

Because commodity prices fluctuate, a royalty valuation should not rely on a single day’s oil or gas price

Many producing oil and gas wells experience changes in production over their productive life.

The decline rate describes how production changes over time.

Consider a simplified example:

  • Year 1 → High production
  • Year 2 → Lower production
  • Year 3 → Continued decline

Later years → Lower but potentially ongoing production

The speed and pattern of decline can influence how much future royalty income an interest may generate.

This is why historical production is generally more informative than looking only at the most recent royalty cheque.

Location can influence the value of an oil and gas royalty.

Properties located in established producing areas may have different development characteristics from properties in areas with limited drilling activity.

Relevant considerations can include:

  • Producing basin
  • Nearby wells
  • Operator activity
  • Geological formation
  • Existing infrastructure
  • Drilling history
  • Potential future development

Location alone does not determine value, but it can provide important context for understanding production and development potential.

A royalty interest may have additional value if the underlying acreage has potential for future wells.

A buyer may investigate:

  • Existing producing wells
  • Permitted wells
  • Undeveloped locations
  • Nearby drilling activity
  • Operator plans
  • Geological characteristics

The Texas Railroad Commission provides online permitting information and production records that can be used when researching oil and gas properties in Texas.

Future development should nevertheless be treated as potential rather than guaranteed.

The lease associated with an oil and gas interest can have a major impact on its economics.

Important provisions may include:

  • Royalty percentage
  • Lease duration
  • Production clauses
  • Pooling provisions
  • Deduction provisions
  • Development obligations
  • Other contractual terms

Two royalty interests located near each other can therefore have different economic characteristics if their underlying contractual arrangements differ.

The Texas Railroad Commission emphasises that lease and royalty matters are private contractual matters and recommends consulting appropriate legal professionals for questions about specific agreements.

The amount of the interest you actually own matters.

You may own:

  • 100% of a mineral interest
  • A fractional mineral interest
  • A royalty interest
  • A non-participating royalty interest
  • Another specific interest defined by legal documents

Texas’s General Land Office explains that mineral ownership can be separated and transferred, and determining ownership requires examining the deeds and lease records affecting the property.

Before evaluating a royalty offer, make sure you know the exact interest represented by the documents.

Not all wells perform the same way.

Two wells in the same general area can have different:

  • Production volumes
  • Decline rates
  • Production histories
  • Operating characteristics
  • Remaining productive lives

For this reason, a royalty valuation should consider the specific wells and interests connected to the royalty rather than relying solely on broad regional averages.

The amount shown on a royalty statement may differ from the gross value of production.

Royalty payment information can include:

  • Severance or other taxes
  • Other deductions
  • Adjustments
  • Gross value
  • Net value

Texas’s royalty guidance identifies these categories among the information that may appear with royalty payments.

Understanding the difference between gross production value and the owner’s actual net revenue is therefore important when assessing a royalty interest.

A royalty interest with clear ownership documentation can be easier to evaluate than one with unresolved title issues.

Potential complications can include:

  • Multiple heirs
  • Old mineral reservations
  • Missing documents
  • Fractional interests
  • Conflicting conveyances
  • Unresolved probate matters
  • Title disputes

The Texas General Land Office explains that mineral ownership is established through the relevant chain of title, including conveyances, reservations, and leases.

Title clarity can therefore be an important part of the transaction process.

While individual buyers use different methods, a simplified valuation framework looks like this:

Current Royalty Income

↓

Production & Decline Analysis

↓

Commodity Price Assumptions

↓

Remaining Production Potential

↓

Lease & Ownership Review

↓

Future Development Assessment

↓

Risk & Market Considerations

↓

Estimated Present Value

The objective is generally to estimate the economic value of expected future royalty income while accounting for uncertainty and timing.

This is why two buyers may potentially arrive at different offers for the same royalty interest.

#RoyaltyRidge #RoyaltyInterest #MineralRights #OilAndGasRoyalties #RoyaltyValuation #MineralOwners #SellingRoyalties #MineralRightsBuyers

If you are considering a valuation or sale, organise the information you already have.

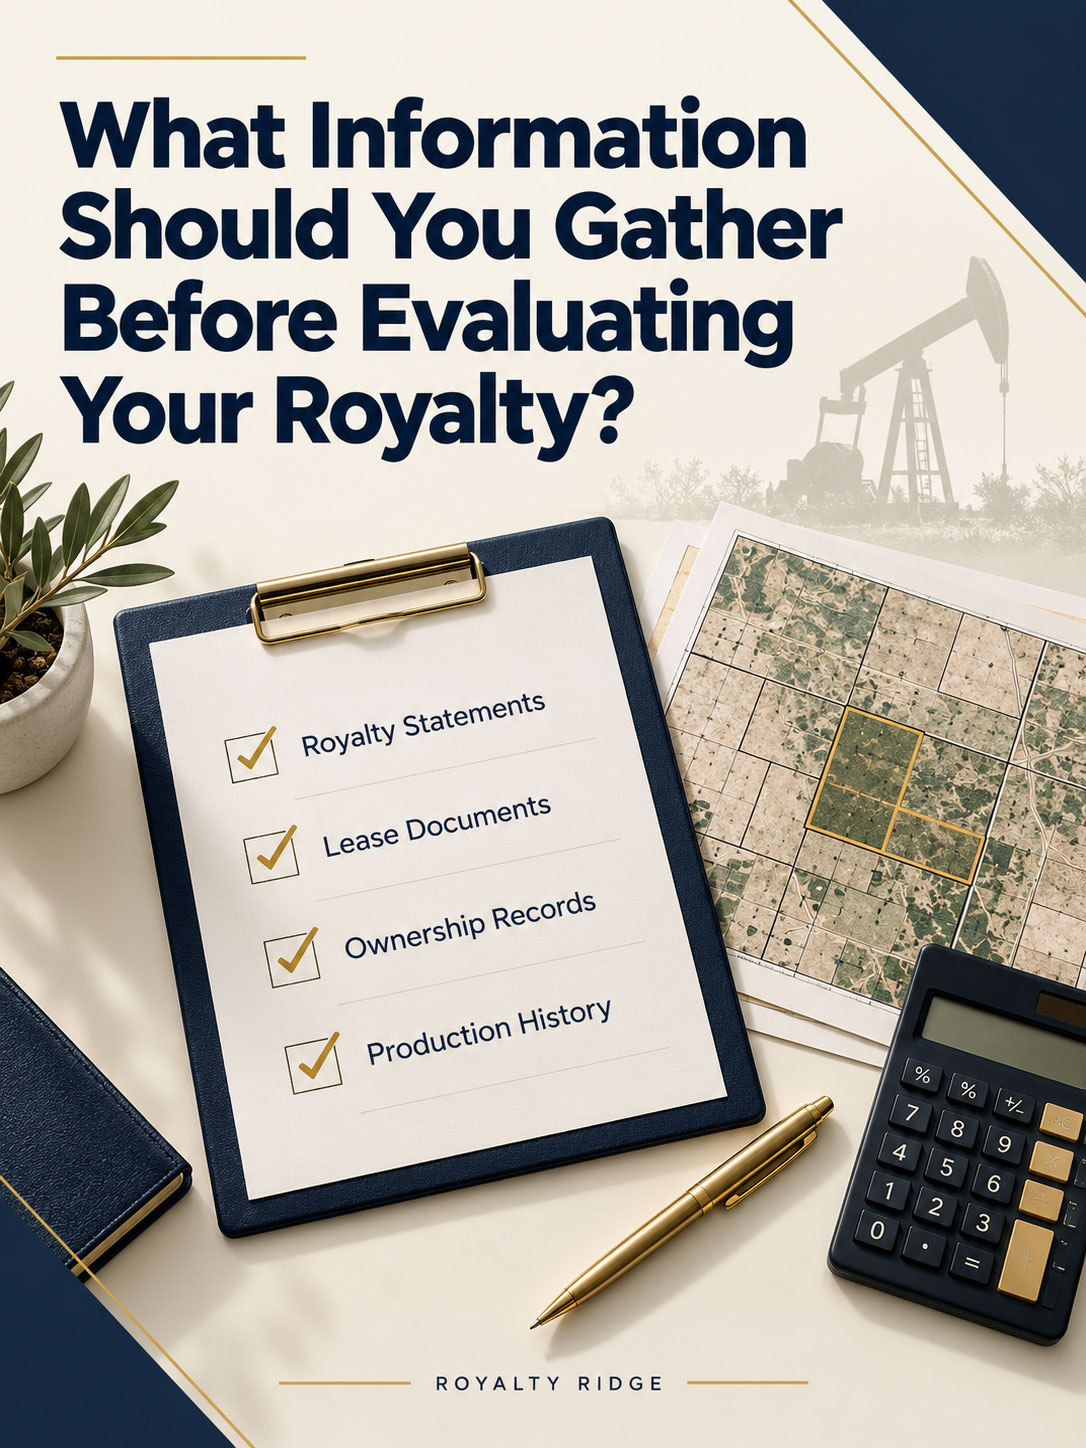
Useful documents include:

  1. Royalty Statements
    Recent statements can show production, revenue, deductions, and ownership information.
  2. Lease Documents
    These can provide important information about royalty terms and other contractual provisions.
  3. Division Orders
    These may identify the owner’s decimal or fractional interest and other payment information.
  4. Deeds and Mineral Documents
    These help establish ownership.
  5. Production Records
    Texas owners can use Railroad Commission records to research reported production and permitting information.
  6. Operator Correspondence
    Notices and communications can sometimes provide additional information about wells or development.
#RoyaltyRidge #RoyaltyInterest #MineralRights #OilAndGasRoyalties #RoyaltyValuation #MineralOwners #SellingRoyalties #MineralRightsBuyers

Not necessarily.

A higher current payment does not automatically mean a royalty interest has a proportionally higher long-term value.

For example, one interest might currently generate more income but be associated with rapidly declining production, while another might generate less today but have stronger remaining production or development potential.

A meaningful valuation therefore considers both current income and expected future economics.

Yes.

Royalty values can change as the underlying asset and market environment change.

Potential influences include:

  • Changes in oil prices
  • Changes in natural gas prices
  • Production increases or declines
  • New wells
  • Additional drilling
  • Changes in reserve estimates
  • Operator activity
  • Market conditions
  • Changes in ownership or lease terms

The EIA notes that reserve estimates themselves can change because of price changes, new discoveries, extensions, purchases and sales, and production.

This helps explain why a royalty interest should be viewed as a changing income-producing asset rather than a fixed commodity.

The value of an oil and gas royalty is influenced by much more than the amount of the latest royalty payment.

The most important factors include:

  1. Current royalty income
  2. Production history
  3. Royalty percentage
  4. Oil and gas prices
  5. Production decline
  6. Remaining production potential
  7. Location
  8. Future development
  9. Lease terms
  10. Ownership percentage
  11. Well performance
  12. Taxes and deductions
  13. Market conditions
  14. Title clarity

For Texas royalty owners, official production and permitting information from the Railroad Commission can provide useful data when researching an interest.

The key is to understand what you own, what it has produced, what contractual rights apply, and what future potential may exist before making a decision about your royalty interest.

Royalty Ridge provides educational resources to help mineral and royalty owners better understand their assets and evaluate their options.

#RoyaltyRidge #RoyaltyInterest #MineralRights #OilAndGasRoyalties #RoyaltyValuation #MineralOwners #SellingRoyalties #MineralRightsBuyers

Frequently Asked Questions

There is no single factor that determines value. Current production, royalty percentage, production decline, commodity prices, future development potential, lease terms, and ownership interest can all influence valuation.

Yes. For oil-producing interests, changes in crude oil prices can affect the revenue generated from production. Oil prices themselves fluctuate with market supply, demand, inventories, and other factors.

Yes. Natural gas prices influence the potential revenue generated from gas production. EIA identifies supply, storage, imports and exports, weather, economic growth, and competing fuels among factors affecting natural gas prices.

Yes. The expected future production profile is an important consideration because royalty value depends partly on future income.

The Railroad Commission of Texas provides reported production information through its Production Data Query system. The Commission also provides online permitting information.

Yes. Buyers may use different assumptions regarding production, commodity prices, development potential, risk, and required returns. As a result, valuations can differ.

Scroll to Top